The government has announced a significant tax relief measure for the cooperative sector by granting a three-year exemption on certain dividend incomes. The move is aimed at strengthening cooperative institutions and reducing their tax burden, especially those operating at the national level.
The announcement comes as part of broader financial and tax reforms discussed during proceedings related to the Finance Bill and follows proposals made in the Union Budget 2026–27.
What the tax exemption includes
Under the new provision, dividend income earned by notified national cooperative federations from investments in companies will be exempt from income tax for a period of three years. This exemption, however, comes with a key condition such income must be distributed further to member cooperatives.
The benefit applies specifically to investments made up to January 31, 2026, ensuring that only eligible and time-bound investments qualify under the scheme.
This measure is expected to prevent double taxation, as dividend income often gets taxed again when passed down to member entities.
Aim: Boost cooperative institutions
The tax relief is part of the government’s ongoing push to strengthen the cooperative movement in India. By reducing the tax burden on dividend income, authorities aim to improve liquidity and enable cooperatives to distribute higher returns to their members.
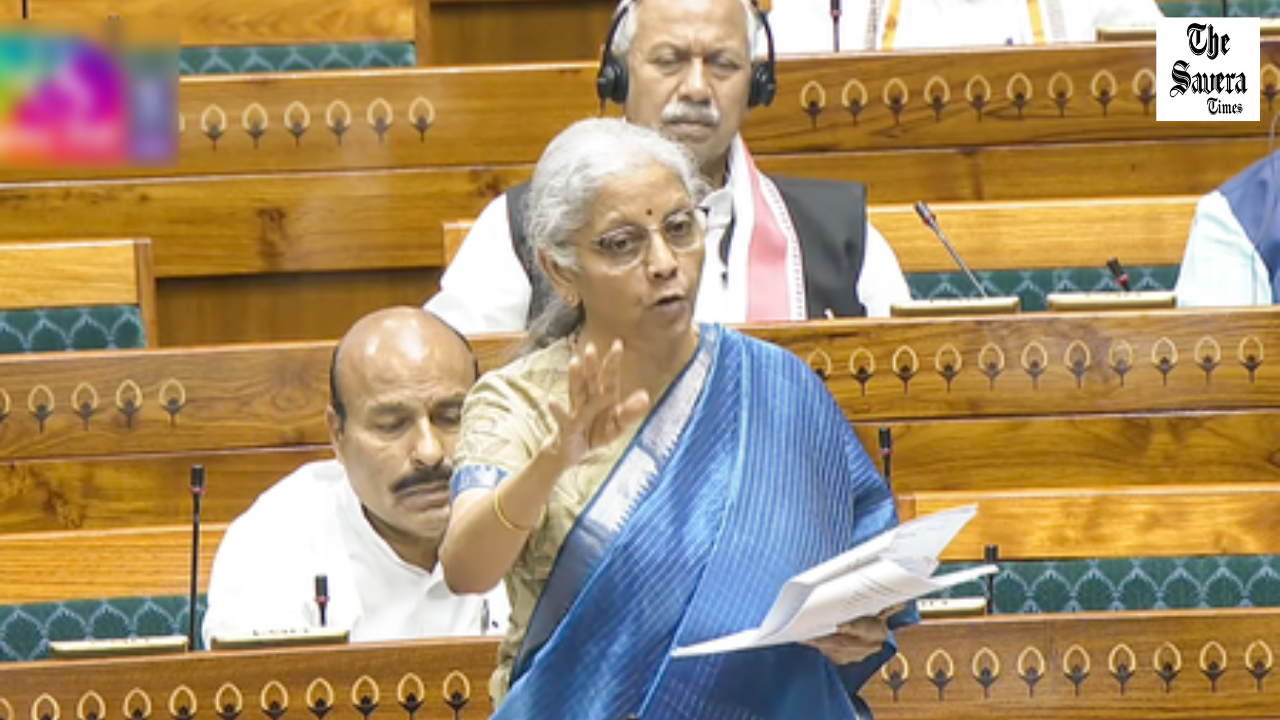
Finance Minister Nirmala Sitharaman had earlier highlighted the need to support cooperative federations, particularly those that operate across states and play a key role in sectors like agriculture, dairy, and rural development.
The policy is also expected to enhance investment capacity within the cooperative ecosystem and encourage reinvestment in growth-oriented activities.
Additional benefits for cooperatives
Apart from the three-year tax exemption, the government has introduced other supportive measures for cooperative societies. These include allowing deductions on inter-cooperative dividend income under the new tax regime, provided the income is distributed to members.
Additionally, deductions have been extended to primary cooperative societies engaged in supplying cattle feed and cotton seed produced by their members, broadening the scope of tax benefits.
These steps collectively aim to create a more favourable tax environment for cooperatives and reduce compliance complexities.
Impact on rural and agricultural economy
Experts believe the tax relief will have a positive ripple effect on rural and agricultural sectors, where cooperatives play a crucial role. Increased earnings and reduced taxation could lead to better financial stability for cooperative bodies, ultimately benefiting farmers and small producers.
The exemption is also expected to encourage cooperative federations to expand investments in companies, knowing that returns in the form of dividends will enjoy temporary tax relief.
Time-bound relief with conditions
While the measure provides a welcome boost, it is strictly time-bound and conditional. The three-year exemption applies only to notified national cooperative federations and is contingent upon the redistribution of dividends to member cooperatives.
This ensures that the benefit directly reaches the grassroots level rather than being retained at the top tier.
Step towards cooperative-led growth
The latest tax relief signals the government’s continued focus on promoting cooperative-led economic growth. By aligning tax policies with the needs of the sector, authorities aim to make cooperatives more competitive and financially resilient.
As implementation begins, stakeholders will be closely watching how effectively the policy translates into tangible benefits for cooperative institutions and their members across the country.