Last Updated: September 17, 2026
Last Updated: September 17, 2026
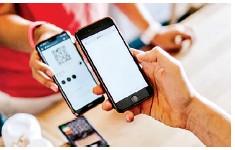
Digital payments in India are often discussed through statistics transaction volumes, user numbers, and technological milestones. Yet their deeper impact is visible in everyday life, where small behavioural shifts are reshaping how people earn, spend, and save. From roadside vendors to small manufacturers, digital payments have become embedded in daily economic activity.
The expansion of mobile internet and affordable smartphones laid the foundation for this change. Platforms enabling instant bank-to-bank transfers and QR-based payments reduced reliance on cash, particularly for small-value transactions. For millions, digital payments are no longer a novelty but a default option.Small businesses have been among the biggest beneficiaries. Digital transactions reduce the need to manage cash, lower risks associated with theft, and simplify record-keeping. Vendors can accept payments from customers without investing in expensive equipment. This ease of use has expanded participation in the formal financial system, even among those previously excluded.
Consumers, too, have adapted quickly. Digital payments offer convenience, transparency, and speed. For migrant workers and informal labourers, instant transfers to families in distant regions reduce dependency on intermediaries. These everyday efficiencies accumulate, subtly improving financial stability for households.
Beyond convenience, digital payments are influencing access to credit. Transaction histories create informal financial footprints, allowing lenders to assess creditworthiness more accurately. Small enterprises that previously lacked documentation can now access micro-loans and working capital. While challenges remain around interest rates and data privacy, the potential for financial inclusion is significant
The Central Bureau of Investigation (CBI) on Thursday accused former West Bengal Education Minister Partha Chatterjee of violating...
The Supreme Court on Thursday directed Indian Oil Corporation Limited (IOCL) to pay Rs 12 lakh compensation to...
A Delhi court on Thursday directed the Cyber Police Station to register an FIR against journalist Karishma Aziz...
Bollywood superstar Salman Khan extended birthday wishes to Prime Minister Narendra Modi as he turned 76 on Thursday....
Good Evening Viewers, stay updated with the latest national, international, Punjab, political, business, entertainment and sports news in...
Two Pakistani Jaish-e-Mohammed (JeM) terrorists were killed in Operation Soan in J&K's Udhampur and have been identified as...
Aries: The day will be auspicious...