Last Updated: October 6, 2026
Last Updated: October 6, 2026
New Delhi: If you hate getting one-time passwords (OTPs) on your phone every time you make a payment, you might soon welcome a new era!
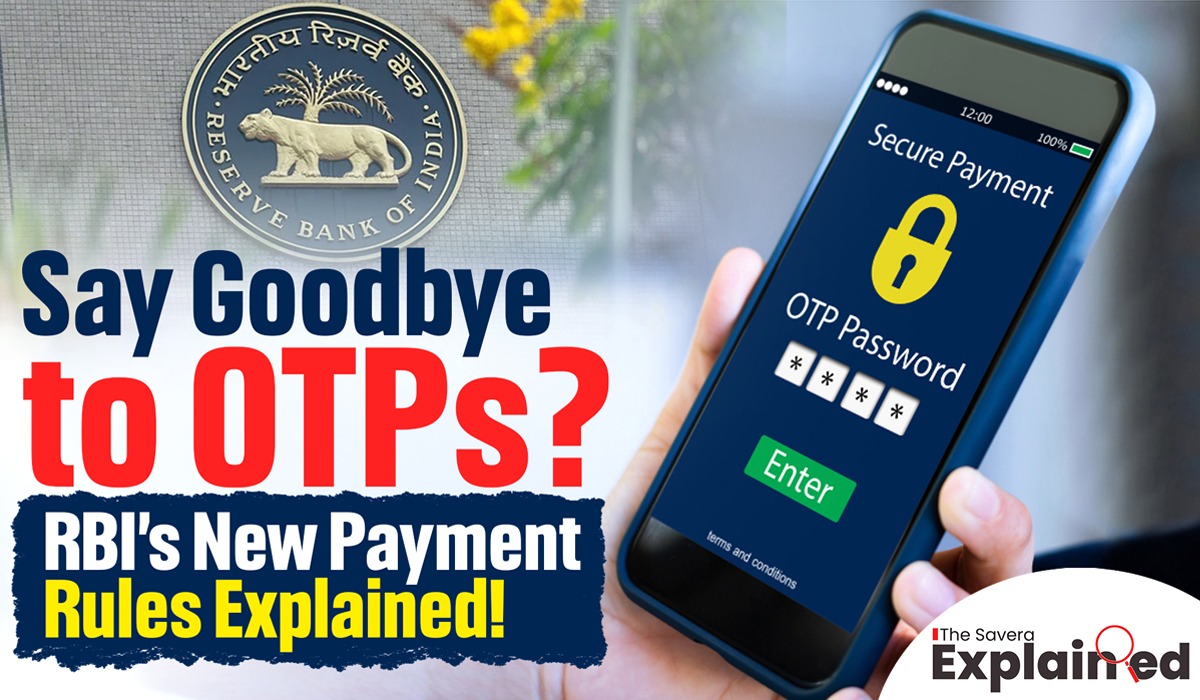
The Reserve Bank of India is shaking things up with new rules that could make OTPs a thing of the past for digital transactions.
Let’s dive into what’s changing, why it matters, and how it’ll affect you!
What’s Happening with OTPs?
Starting April 1, 2026, the RBI’s Authentication Directions, 2025 will kick in, and they’re loosening the grip on OTPs as the default second factor for securing digital payments.
Two-factor authentication, or 2FA, will still be mandatory, but banks and payment platforms can now explore alternatives to SMS-based OTPs.
This doesn’t mean OTPs are gone for good—they’ll still be an option.
But the RBI is encouraging the payments ecosystem to adopt more secure and flexible methods to keep up with evolving tech and rising fraud risks.
As Vishwas Patel, chairman of the Payments Council of India, told The Times of India, “The recently released AFA Directions strike an important balance between consumer security and innovation.”
What Could Replace OTPs?
So, what’s replacing those pesky OTPs? The RBI says authentication can now come from three categories: something you know (like a password or PIN), something you have (like a card or software token), or something you are (like your fingerprint or other biometrics).
This could mean using face ID, device-based authentication, or even Aadhaar-based biometrics for seamless payments.
The catch? At least one of these factors must be dynamic—unique to each transaction—to ensure top-notch security. For example, instead of a static password, you might use a one-time code generated by your banking app or a biometric scan that’s verified in real-time.
This makes it harder for fraudsters to crack the system, even if one layer is compromised.
Why the Change?
Why fix what’s not broken? Well, OTPs aren’t foolproof. They can be intercepted by scammers or delayed by network issues.
The RBI first floated this idea in February 2024, pointing out that digital payments have evolved enough to support stronger alternatives.
The new rules also emphasize risk-based checks. Banks can now analyze your spending patterns, location, or device details to flag suspicious transactions.
For high-risk payments, they might even use platforms like DigiLocker for extra confirmation.
And here’s the best part: if a bank messes up and you lose money due to their failure to follow these rules, the RBI says you’ll be fully compensated—no questions asked!
What About Global Transactions?
For those shopping on international websites, there’s a new safeguard. From October 1, 2026, card issuers will need systems to validate “card-not-present” cross-border transactions when the authentication request comes from an overseas merchant.
This means safer online shopping abroad, with an extra layer of protection against fraud.
So, get ready for a future where payments could be faster, safer, and less annoying—no more waiting for OTPs! What do you think about these changes? Are you excited for biometric payments or sticking to OTPs? Drop your thoughts in the comments, and don’t forget to like and subscribe for more updates! See you next time!
Imagine being seriously injured inside a flying aircraft, with blood on your clothes, passengers in panic and the...
Imagine the world’s biggest diesel exporter turning off its export taps. That is the concern after US President...
For India’s pharmaceutical industry, the latest US tariff decision brings relief — but not across the entire medicines...
One handshake, two superpowers and a long list of disagreements. US President Donald Trump and Chinese President Xi...
A river does not understand borders. But when two countries sharing that river are locked in a long-running...
A voter list revision — and now a software controversy A voter may have the right to vote,...
Aries: The day will be auspicious...